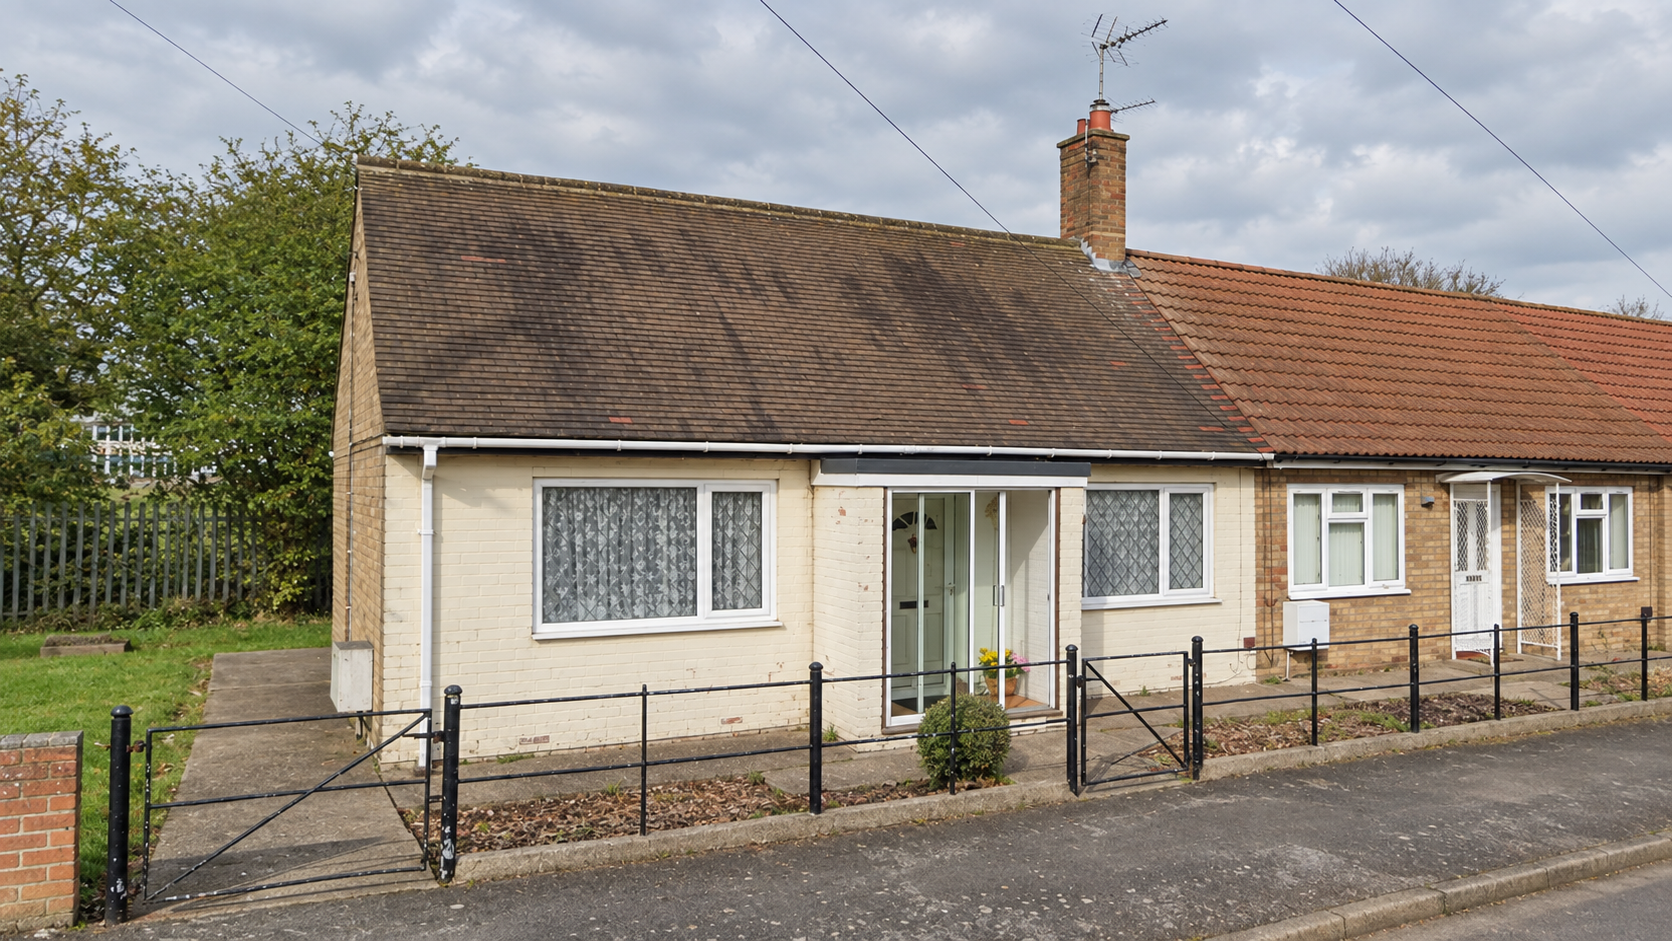
Hull, East Yorkshire — security property
£40,000 Refurbishment Bridging Loan. Enquiry to Completion in 16 Days.
A limited company — directed by an experienced contractor — identified an end-terrace bungalow in Hull available via Modern Method of Auction for £47,000. The company had a track record of completing refurbishments, a clear works plan, and an existing property portfolio with ongoing sales to service the exit. Previous lenders had charged upfront fees and failed to deliver. AF Credit provided a £40,000 bridging facility — 85% of the purchase price — using an AVM with all costs rolled in and nothing required upfront.
Hull, East Yorkshire — security property
| Item | Detail |
|---|---|
| Purchase Price | £47,000 |
| Sale Method | Modern Method of Auction (iamsold) |
| Reservation Fee (auction) | £6,600 — paid to iamsold on exchange |
| Gross Facility | £40,000 |
| LTV vs Purchase Price | 85% |
| Property Type | One-bedroom end-terrace bungalow |
| Location | Hull, East Yorkshire |
| Materials / Refurb Cost | ~£10,000 (self-managed by borrower) |
| Anticipated GDV | ~£85,000 |
| Valuation Method | AVM — no upfront valuation fee |
| Completion Time | 16 days from initial enquiry |
| Borrower Profile | Limited company — experienced contractor, adverse credit |
| Loan Structure | Single drawdown — maximum day-one advance |
| Upfront Costs to Borrower | None — all fees rolled into facility |
| Exit Strategy | Proceeds from low-leverage portfolio sales |
A limited company with an experienced contractor director had identified an end-terrace bungalow in Hull available via the Modern Method of Auction (iamsold) for £47,000. The property required cosmetic refurbishment with a materials budget of approximately £10,000 — work the director intended to manage and self-deliver, with a track record of completing similar projects.
The MMA purchase structure added urgency. A non-refundable reservation fee of £6,600 had already been paid to iamsold on exchange — a sum that cannot be recovered if a lender fails to perform. The company had already experienced this with a previous lender, having also incurred approximately £2,000 in legal costs that came to nothing. The hard completion deadline was 3 September 2026 — sixteen days away.
The requirements were clear: maximum net advance on day one, a single drawdown with no future staged releases, an AVM to avoid further upfront costs, and a straight answer on whether the deal was supportable before any further commitment. Adverse credit was on the company director's record, and the application needed a non-status, asset-led lender.
The exit was not dependent on the sale of the Hull property. The borrower held a portfolio of properties elsewhere with low leverage — ongoing sales within that portfolio were generating sale proceeds sufficient to repay the bridging facility. This gave the exit a degree of independence from the refurbishment programme on the security property itself, and materially strengthened the overall case.
The anticipated post-refurbishment value of approximately £85,000 provided a clear picture of the equity position and demonstrated the quality of the underlying asset — but the repayment mechanism was already in motion through the portfolio.
AF Credit assessed the transaction on its fundamentals. The LTV of 85% against the purchase price was high, but the quality of the underlying opportunity, the borrower's demonstrable track record as a contractor, the self-managed refurbishment plan, and the portfolio-backed exit gave us clear confidence to proceed.
Same-day indicative terms were issued on 18 August 2026. We confirmed from the outset whether the deal was supportable and set out all costs clearly — exactly what the borrower needed having been let down previously. An AVM was instructed immediately, removing any further upfront cost. All arrangement fees and monthly interest were rolled into the gross facility of £40,000, with the full net advance released on the completion date and nothing required from the borrower beforehand.
Report on title was received on Friday 28 August. Completion followed on 3 September 2026 — on the contractual deadline, sixteen days after the initial enquiry.
The purchase completed on deadline. The borrower received the full net advance on day one with no upfront outlay to AF Credit at any stage. The single-drawdown structure meant the refurbishment could commence immediately, funded from the borrower's own materials budget, with no further interaction with the lender required during the works.
The portfolio sales providing the exit were already progressing — the bridging facility provided a short-term bridge to a defined and credible repayment event already in motion.
Cases with adverse credit and high LTV against purchase price require a strong compensating case across all other factors. Here, several elements came together:
Yes. AF Credit is an asset-led lender. We assess applications primarily on the strength of the property transaction and the credibility of the exit strategy, rather than relying on conventional credit scoring. We regularly consider cases involving CCJs, defaults, missed payments and discharged bankruptcy. Each application is reviewed individually — adverse credit does not automatically exclude a borrower from consideration.
Yes. Because AF Credit lends on a non-status basis, provable income history is not a prerequisite for borrowing. We look at the quality of the security, the loan-to-value ratio and the realism of the proposed exit. Newly self-employed borrowers are regularly considered where the underlying deal is strong.
An AVM (automated valuation model) uses comparable market data to arrive at an estimated property value without the need for a physical inspection. AF Credit can use AVMs in appropriate cases, removing the need for an upfront valuation fee. AVM suitability depends on property type, location and loan size — contact us to discuss your specific situation.
Yes. AF Credit can roll the arrangement fee and monthly interest into the gross facility so that the borrower is not required to pay any costs upfront. The fees are deducted from the gross loan, with the balance (the net advance) released on completion. All costs are settled from the sale or refinance proceeds on redemption.
AF Credit can provide same-day indicative terms and, in appropriate cases, complete a bridging loan in as little as 7–21 days from initial enquiry. In this case, completion was achieved in 16 days, meeting the borrower's contractual deadline of 3 September 2026.
Adverse credit was on record and was considered in full — it was not ignored. It was assessed in the context of a borrower whose professional track record, exit credibility and asset quality provided strong compensating factors. This is what asset-led underwriting looks like in practice.
RelatedAF Credit lends on the deal, not just the borrower. If the security is strong and the exit is credible, we want to hear from you — and we'll give you a straight answer the same day.
Get an instant quoteDisclaimer: This case study reflects a real completed transaction. Client details have been anonymised to protect confidentiality. All lending is subject to underwriting and credit approval is not guaranteed. Any property used as security may be repossessed if you do not repay your loan within the agreed term. AF Credit provides unregulated bridging finance only — loans secured on your main residence are not available. AF Credit is a trading style of Avalon Financial Limited, Company No. 15786496.