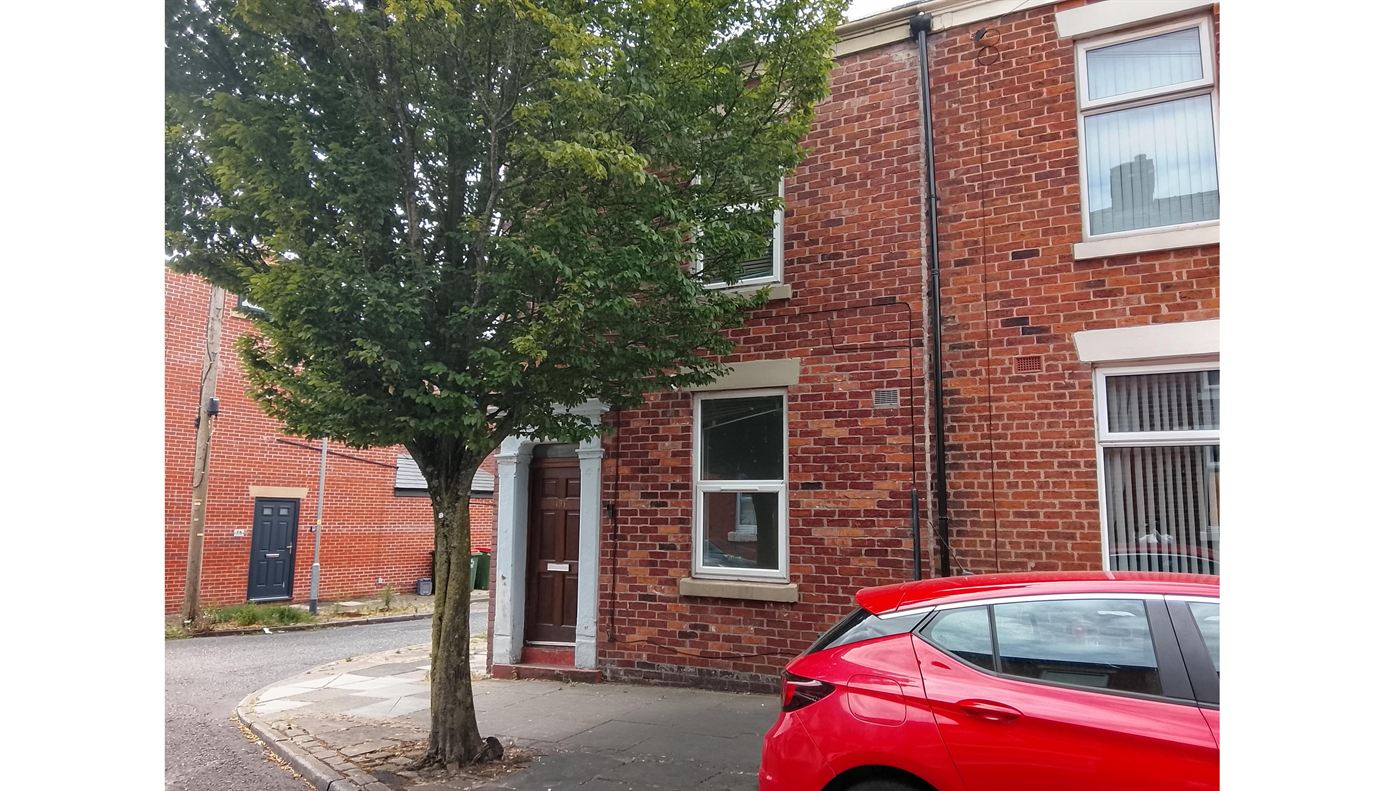
Preston, Lancashire — security property
A tenanted auction purchase with a 25-year lease and a live rent dispute sitting on the title.
The buyer needed a lender that would fund the property exactly as it stood — encumbered, tenant in place, no vacant possession — and would say so in writing before she spent another penny. One specialist lender had already read the legal pack and declined at application stage. We read the same pack, asked two questions, and issued terms the same morning. The borrower then stayed with a second lender that never got moving, came back to our terms with about a week left, and completed on the deadline of 22 September 2026.
Preston, Lancashire — security property
| Item | Detail |
|---|---|
| Transaction Type | Auction purchase — tenanted, no vacant possession |
| Location | Preston, Lancashire |
| Property Type | Freehold end-terrace house |
| Charge | First charge |
| Property Value | £87,000 |
| Gross Facility | £65,250 |
| LTV | 75% |
| Monthly Rate | 1.25% per month, fixed |
| Term | 9 months |
| Interest Treatment | Retained — 9 months deducted at source (£7,341) |
| Net Advance | £52,476 |
| Final Repayment | £66,066 |
| Valuation Method | Desktop valuation |
| Legal Structure | Dual representation — one firm acting for borrower and lender |
| Enquiry to Written Terms | 42 minutes |
| Exit Strategy | Refinance once the lease position resolves |
Underwritten and funded by AF Credit as principal. This case study concerns a £65,250 unregulated bridging facility secured by first charge on an investment property in Preston. Borrower details have been anonymised.
The buyer had taken a freehold end-terrace in Preston at auction in August 2026 for £87,500, in her personal name. Auction purchases run to a fixed completion date and strict special conditions — miss it and the deposit goes with it.
The complication was on the title. The property was subject to a 25-year social housing lease, and the leaseholder was in significant arrears with a live rent dispute running. The seller had indicated the lease would be surrendered before completion, but an auction contract is not the place to rely on an indication. If the surrender did not happen in time, the buyer would still be obliged to complete — with the lease, the tenant and the dispute all still in place.
That produced a single, non-negotiable requirement: the lender had to fund the property exactly as it stood, encumbered, with no lease-surrender or vacant-possession condition attached to the offer. And it had to confirm that in writing, before any non-refundable fee was incurred.
This was not a theoretical concern. One specialist lender had already given indicative terms on the property as-is, then declined at application stage once its own legal review reached the lease. That is an expensive way to find out. A second application was running elsewhere at the same time, and it would spend the next fortnight going nowhere.
The enquiry arrived at 10:24 in the morning. We asked two questions: what the rent dispute actually was, and what the leaseholder was paying against what the lease obliged them to pay. Both were answered within five minutes.
That was genuinely all we needed to form a view. The dispute was about arrears, not about the validity of the lease or the title. An arrears dispute affects income, and income was not our exit — a refinance was. The security was a freehold house in a known market, with the lease fully documented in the auction pack. At the LTV we were discussing, there was room for the lease to weigh on value and the loan still to sit comfortably.
Written terms were issued at 11:06. Forty-two minutes from first contact, with the lease position accepted explicitly and in writing, before the borrower had committed to a single non-refundable cost.
We put the legal question where it belonged. We did not ask for the dispute to be resolved. We asked our solicitors to confirm two things. That our position as lender was protected. And that no liability from the dispute, the side letter or the management arrangements could pass to us. That is a question a lawyer can answer by reading the pack, which is exactly what the previous lender had used as grounds to withdraw.
We used dual representation. One firm acted for borrower and lender, covering the lender's legals, the borrower's financing legals and the purchase itself. On an auction deadline, removing a second firm from the chain removes a week of duplication.
This facility priced at 1.25% per month, above the rate a straightforward case attracts. We would rather explain that than bury it.
AF Credit prices to complexity and timescale, not to loan size alone. A clean security with a clear title, a standard LTV and a comfortable deadline sits at the bottom of our range. This case carried an encumbered title, a live dispute, an auction clock and a legal review that had already defeated one lender. It took more underwriting and more legal work, and it was priced for what it was.
The important part is that the price, the fees and the deductions were all set out in writing at 11:06 on day one, and did not move afterwards. A cheap rate quoted by a lender who withdraws three weeks later costs considerably more than an honest one quoted in the first hour.
Yes. AF Credit lends on tenanted property, including stock bought at auction where vacant possession is not available on completion. The questions we ask are whether the tenancy or lease is clearly documented, what it does to the value and saleability of the security, and whether the borrower's exit still works with the tenant in place. See our auction bridging loans page.
Many will not, and some withdraw at application stage once the legal pack is read. AF Credit can lend where a dispute exists provided our position as lender is properly protected and we do not take on any liability arising from the dispute. That is a legal question to be answered by reading the pack, not a reason to decline on sight.
Where the facts are clear, terms can be issued within the hour. On this Preston case the first email arrived at 10:24 and written terms were issued at 11:06 the same morning. The borrower then committed about a week before the auction deadline and the facility completed on that deadline. Timescales depend on the individual case and on how quickly the information we ask for comes back.
Dual representation means one firm of solicitors acts for both borrower and lender. It removes the duplication of two firms reviewing the same auction legal pack and reporting separately, which on a 28-day auction deadline can be the difference between completing and losing the deposit.
AF Credit prices to the complexity and the timescale of the case, not just the loan to value. A clean, standard security at a sensible LTV sits at the lower end of our range. A case carrying an encumbered title, a live dispute and a fixed auction deadline takes more underwriting and more legal work, and is priced accordingly. The pricing is set out in writing before any cost is incurred — you can model your own figures on our bridging loan calculator.
Nothing here required a leap of faith. It required reading the legal pack and deciding which risks actually bore on repayment. The lease looked alarming on a checklist and turned out to be manageable on the facts — which is the difference between underwriting a case and scoring one. More completed transactions are set out in our bridging loan case studies.
RelatedTenanted, encumbered, disputed or simply unusual — send the legal pack and we will give you a written answer on whether we can fund it as it stands, before you commit to any cost.
Get an instant quoteDisclaimer: This case study reflects a real completed transaction. Client details have been anonymised to protect confidentiality. All lending is subject to underwriting and credit approval is not guaranteed. Rates are set case by case and reflect complexity, security and timescale. Any property used as security may be repossessed if you do not repay your loan within the agreed term. AF Credit provides unregulated bridging finance only — loans secured on your main residence are not available. AF Credit is a trading style of Avalon Financial Limited, Company No. 16865484.